CarInsurance.com Insights
- Name Your Price changes your coverage, not Progressive’s rates, and it can’t match another insurer’s quote.
- Comprehensive and collision make up most of the slider’s range. On Progressive’s 2026 averages, dropping both from a $1,000-deductible full-coverage policy reduces the yearly price from $2,313 to $864.
- Cutting liability from 50/100/50 to your state’s minimum saves Progressive drivers about $112 a year on average, roughly $9 a month. In 35 out of 42 states and Washington, D.C in our data, that step is worth less than $150 a year.
- For full coverage, Progressive’s $2,569 yearly average (with $500 comprehensive/collision deductibles) ranks fourth of seven widely available carriers. Travelers averages $1,962.
It’s time to renew your car insurance and your rates went up, even though nothing’s changed. Still the same car, still the same (clean) driving record, still the same you. So when you see an ad that says you can name your own rate, it sounds pretty good.
Here’s the thing: Progressive’s Name Your Price tool doesn’t lower Progressive’s prices; it just remixes your coverage. You enter the amount you’d like to pay, and the tool adjusts your liability limits, deductibles, and coverage types until the quote matches your number. It’s useful, but it’s not a discount, and it can’t match a quote you got from another company.
The focus becomes the end price instead of finding the right coverage, and it’s too easy to miss what you give up when you move that slider around. We put a price on every slider position using Progressive’s 2026 averages and ran the tool ourselves several times to see what happened. Here’s what we found.

How does Progressive’s Name Your Price tool work?
Name Your Price is an optional editor inside Progressive’s online quote process. After you enter your driver and vehicle details, you type the amount you’d like to pay, and Progressive shows a coverage package at or near that number. You can then adjust individual coverages before you buy.
Here’s how it plays out:
- Get a quote. Progressive uses your details to work out the lowest and highest prices it can offer you.
- Name your price. Enter what you want to pay, and Progressive builds a package that fits.
- Adjust, then decide. Change limits or deductibles until the coverage fits your life, then buy or walk away.
As you move the slider, other aspects of the quote change, too. The liability limits might lower as the price lowers, and collision and comprehensive might disappear altogether. Raise the price higher, and those coverages come back, and your limits might go up, too.
There are guardrails, too. You can’t pick a price that puts your coverage below what the state’s minimum liability law allows. If you name a number outside Progressive’s range, you’ll see the closest package it can build.
Progressive says the tool is available in most states, though you may not spot it at first. When I ran a quote, I needed to scroll all the way down to the bottom, under “more ways to save.
Is Name Your Price a price-matching tool?
No. Progressive clearly states that Name Your Price isn’t a price-matching tool and that it can’t match quotes from other insurers. The number you name only changes how much Progressive coverage you get. If another company quoted you less for the same coverage, the tool won’t bring Progressive’s price down to meet it.
Different insurers can price the same driver very differently. For example, one company might charge you hundreds of dollars less per year for the same limits and deductibles. The Name Your Price tool can’t see what other insurers offer you, only what it can offer you for the price.
If you were hoping to name a lower price and get the same coverage, you’ll want to compare rates across companies instead. We show how Progressive stacks up against other carriers below.
What you give up when you slide the price down
When you enter a lower price, the tool can make three adjustments: your deductible amount, whether you get comprehensive and collision coverage, and your liability limits. But these adjustments don’t move the price equally. Using Progressive’s 2026 average rates, we found the value of each step down.
| Coverage level | Progressive avg. per year | Insurance cost per month | Saved vs. the row above |
|---|---|---|---|
| Full coverage, $250 deductible | $2,972 | $248 | n/a |
| Full coverage, $500 deductible | $2,569 | $214 | $403 |
| Full coverage, $1,000 deductible | $2,313 | $193 | $256 |
| Liability only, 50/100/50 | $864 | $72 | $1,449 |
| State minimum liability | $752 | $63 | $112 |
Achieving the biggest savings requires skipping comprehensive and collision. Dropping both and decreasing your coverage limit from 100/300/100 to 50/100/50 helps you save $1,449 per year, more than all other steps combined. Next are the deductibles, with smaller savings each time you raise them. Changing your liability coverage, which protects your savings and paycheck if you hurt someone, saves the least.
Liability limits
Liability pays for the other person’s injuries and property damage when a crash is your fault. Lower limits mean your policy doesn’t pay out as much, leaving you on the hook for the rest.
Comprehensive and collision
These coverages help pay to fix or replace your own car after a crash, theft, hail damage, or striking a deer. If you have a loan or lease, your lender almost certainly requires you to have them. If your car is older and you could replace it using your savings, dropping these can make sense.
Your deductible
This is what you pay first before insurance kicks in. Raising it lowers your price, but the savings shrink as you go. Changing your deductible from $250 to $500 saves $403 per year, but raising it from $500 to $1,000 saves just $256 per year. Only raise it to a number you could pay tomorrow without borrowing, or finance charges could eat up any savings you get.
Speak with a friendly agent and get your quote in minutes!


The slider move that saves little and risks the most
Saving money is all well and good until the slider drops your liability coverage to your state’s minimum. If that happens, push back. Based on Progressive’s 2026 averages, state-minimum liability costs $752 per year, and 50/100/50 liability costs $864. That’s about $112 a year, or roughly $9 a month, for twice the protection in many states.
Dropping your liability too far leaves a sizable gap you’ll need to cover out of your own pocket after a crash. Say your policy pays up to $25,000 per injured person, and you cause a crash in which the other driver’s medical bills total $60,000. Your insurer pays $25,000. According to the NAIC, if the driver sues you for more than your policy limits, you’re responsible for the difference — $35,000, in this case.
State minimum coverage is just that: the bare minimum that keeps you legal on the road. Before you let the slider assign you minimum coverage, see where else you can cut back.
Sophie’s Tip
Need to trim? Start with your deductible, not your liability. On Progressive’s averages, going from a $500 to a $1,000 deductible cut full coverage by $256 a year, and you only pay that deductible if you file a claim.
How much the liability step increase costs in your state
In 35 out of 42 states and Washington, D.C in our data, moving up from the state minimum to 50/100/50 liability costs Progressive drivers less than $150 a year. In a handful of states, it costs much more, and in a few, it costs almost nothing.
This table shows the price difference between Progressive’s state minimum coverage and 50/100/50 liability for several states, ranging from an extra $589 annually in Louisiana to no difference in North Carolina. That’s because North Carolina’s state minimum limits are already at 50/100/50. State minimums are very close to that in Maine, Alaska, and Virginia, where they’re set at 50/100/25.
| State | State minimum | 50/100/50 liability | Extra per year for 50/100/50 |
|---|---|---|---|
| Louisiana | $1,032 | $1,621 | $589 |
| Florida | $1,642 | $2,133 | $491 |
| Maryland | $1,106 | $1,424 | $318 |
| Nevada | $859 | $1,110 | $251 |
| Rhode Island | $745 | $965 | $220 |
| Virginia | $1,106 | $1,117 | $11 |
| Alaska | $567 | $571 | $4 |
| Maine | $405 | $408 | $3 |
| North Carolina | $535 | $535 | $0 |
Find your own state in the full table under “Progressive’s average prices by state”
What price should you name?
It can be tough to pull a number out of thin air. The goal should be to find the price that buys the coverage you need, not just the lowest price Progressive lets you pick.
For context, here are the average Progressive rates for 2026 for each level of protection.
- Liability only, 50/100/50: About $864 a year ($72 a month). A sensible floor if your car is paid off and inexpensive to replace.
- Full coverage, $1,000 deductible: About $2,313 a year ($193 a month). Covers your own car, too, at the lowest full-coverage price.
- Full coverage, $500 deductible: About $2,569 a year ($214 a month). CarInsurance.com’s standard full coverage benchmark.
Remember, your rates will vary depending on your driving history, vehicle, age, ZIP code, and other variables.
If you’re still paying on the car (whether it’s leased or financed), you’ll need full coverage. If you’re not, then you can start with liability only.
Before you run the Name Your Price tool, make sure you know what coverage you have now and what you need to buy:
- Pull your current declarations page: This lets you check what you’re already paying for.
- List your non-negotiables: That’s comprehensive and collision if you have a loan or lease, liability of at least 50/100/50, and a deductible you could afford to pay tomorrow.
- Check the discounts you qualify for: A discount lowers the price without cutting coverage, and Progressive offers discounts for a wide range of things.
- Name your price, then compare: Run down Progressive’s offer to your list line by line. If something on your list is missing, the number was too low.
Sophie’s Tip
Before you type a number, pull up your current declarations page. It’s a one-page summary of your coverage. Name Your Price is much easier to judge when you can compare its package line by line with what you already have.
Progressive’s average prices by state
Prices vary a lot by state, so it’s helpful to use your state’s numbers as your starting point. In the table below, see Progressive’s average rates by state and coverage level.
| State | State minimum | 50/100/50 liability | Full coverage ($1,000 deductible) | Full coverage ($500 deductible) |
|---|---|---|---|---|
| Alabama | $584 | $698 | $2,355 | $2,503 |
| Alaska | $567 | $571 | $1,630 | $1,832 |
| Arizona | $1,515 | $1,692 | $3,047 | $3,193 |
| Arkansas | $680 | $828 | $3,286 | $3,619 |
| California | $583 | $632 | $2,616 | $3,013 |
| Colorado | $483 | $596 | $2,305 | $2,695 |
| Connecticut | $1,464 | $1,597 | $2,992 | $3,323 |
| Delaware | $1,160 | $1,259 | $2,421 | $2,620 |
| Florida | $1,642 | $2,133 | $5,425 | $5,676 |
| Georgia | $726 | $823 | $1,697 | $1,807 |
| Hawaii | $536 | $625 | $1,277 | $1,332 |
| Illinois | $519 | $575 | $1,542 | $1,699 |
| Indiana | $418 | $443 | $1,272 | $1,486 |
| Iowa | $370 | $421 | $1,684 | $1,930 |
| Kansas | $665 | $735 | $1,734 | $2,031 |
| Kentucky | $1,051 | $1,124 | $2,482 | $2,779 |
| Louisiana | $1,032 | $1,621 | $4,982 | $5,206 |
| Maine | $405 | $408 | $1,522 | $1,827 |
| Maryland | $1,106 | $1,424 | $2,363 | $2,445 |
| Massachusetts | $891 | $961 | $1,896 | $2,170 |
| Michigan | $937 | $1,088 | $2,672 | $2,946 |
| Mississippi | $592 | $730 | $2,354 | $2,545 |
| Montana | $540 | $589 | $2,352 | $2,775 |
| Nebraska | $506 | $587 | $2,097 | $2,389 |
| Nevada | $859 | $1,110 | $3,594 | $4,069 |
| New Hampshire | $572 | $612 | $1,379 | $1,548 |
| New Jersey | $1,370 | $1,460 | $2,781 | $3,069 |
| New Mexico | $715 | $797 | $2,473 | $2,845 |
| New York | $622 | $689 | $1,206 | $1,258 |
| North Carolina | $535 | $535 | $1,290 | $1,460 |
| North Dakota | $639 | $688 | $1,774 | $2,190 |
| Oklahoma | $400 | $456 | $1,966 | $2,241 |
| Oregon | $743 | $852 | $1,431 | $1,539 |
| Pennsylvania | $604 | $753 | $2,630 | $2,884 |
| Rhode Island | $745 | $965 | $2,270 | $2,523 |
| South Carolina | $791 | $907 | $2,480 | $2,632 |
| South Dakota | $228 | $254 | $1,726 | $2,270 |
| Texas | $895 | $958 | $2,704 | $3,105 |
| Utah | $807 | $873 | $2,022 | $2,260 |
| Virginia | $1,106 | $1,117 | $2,350 | $2,660 |
| Washington | $600 | $708 | $2,407 | $2,557 |
| Washington, D.C. | $1,408 | $1,521 | $3,763 | $4,346 |
| West Virginia | $940 | $1,136 | $2,283 | $2,530 |
Not every state is in our data. If yours isn’t listed, use the national figures above as a rough guide.
Is Name Your Price cheaper than shopping around?
Not always. Because Name Your Price can only rearrange Progressive’s coverage to fit a number, the only way to know whether your price is a good deal is to check what other companies charge for the same coverage. Progressive is midrange compared to its competitors for full coverage – cheaper than Farmers, Allstate and State Farm, and more expensive than Travelers, GEICO and Nationwide.
The table below shows how Progressive’s 2026 averages compare with other widely available insurers.
| Insurer | Full coverage ($500 deductible) | Liability only (50/100/50) | State minimum |
|---|---|---|---|
| Travelers | $1,962 | $833 | $767 |
| GEICO | $2,159 | $651 | $539 |
| Nationwide | $2,524 | $941 | $932 |
| Progressive | $2,569 | $864 | $752 |
| State Farm | $2,875 | $1,139 | $1,025 |
| Allstate | $3,159 | $1,059 | $946 |
| Farmers | $3,207 | $1,064 | $950 |
| USAA* | $1,628 | $465 | $406 |
*USAA is available only to military members, veterans and their eligible family members.
You’ll start to notice a pattern: Progressive ranks fourth for full coverage, third for liability only and second for state minimum. In other words, it gets more competitive as you buy less coverage. Sliding your price down can make Progressive look like a bargain, but it’s also at a coverage level where you’re more exposed.
For full coverage, Travelers averaged $607 less per year than Progressive. For liability only and state minimum, GEICO averaged $213 less. Your own numbers will differ, so compare quotes for the same coverage before you settle on a particular price.
What happened when we used Name Your Price?
In October 2026, I ran Progressive’s quote tool to see for myself. I started my quote using my real information: 47 years old, living in Pennsylvania, with a clean driving record, a 2025 Subaru and a husband and a teenager, each with their own vehicles. I tried Name Your Price four ways: based on my current coverage with another provider, then 20% lower, 20% higher, and as low as it would go.
Later, I tried to slide the tool as low as it would go, but shifting my price 20% lower had already gotten me to the floor of what was available.
A closer look at the numbers
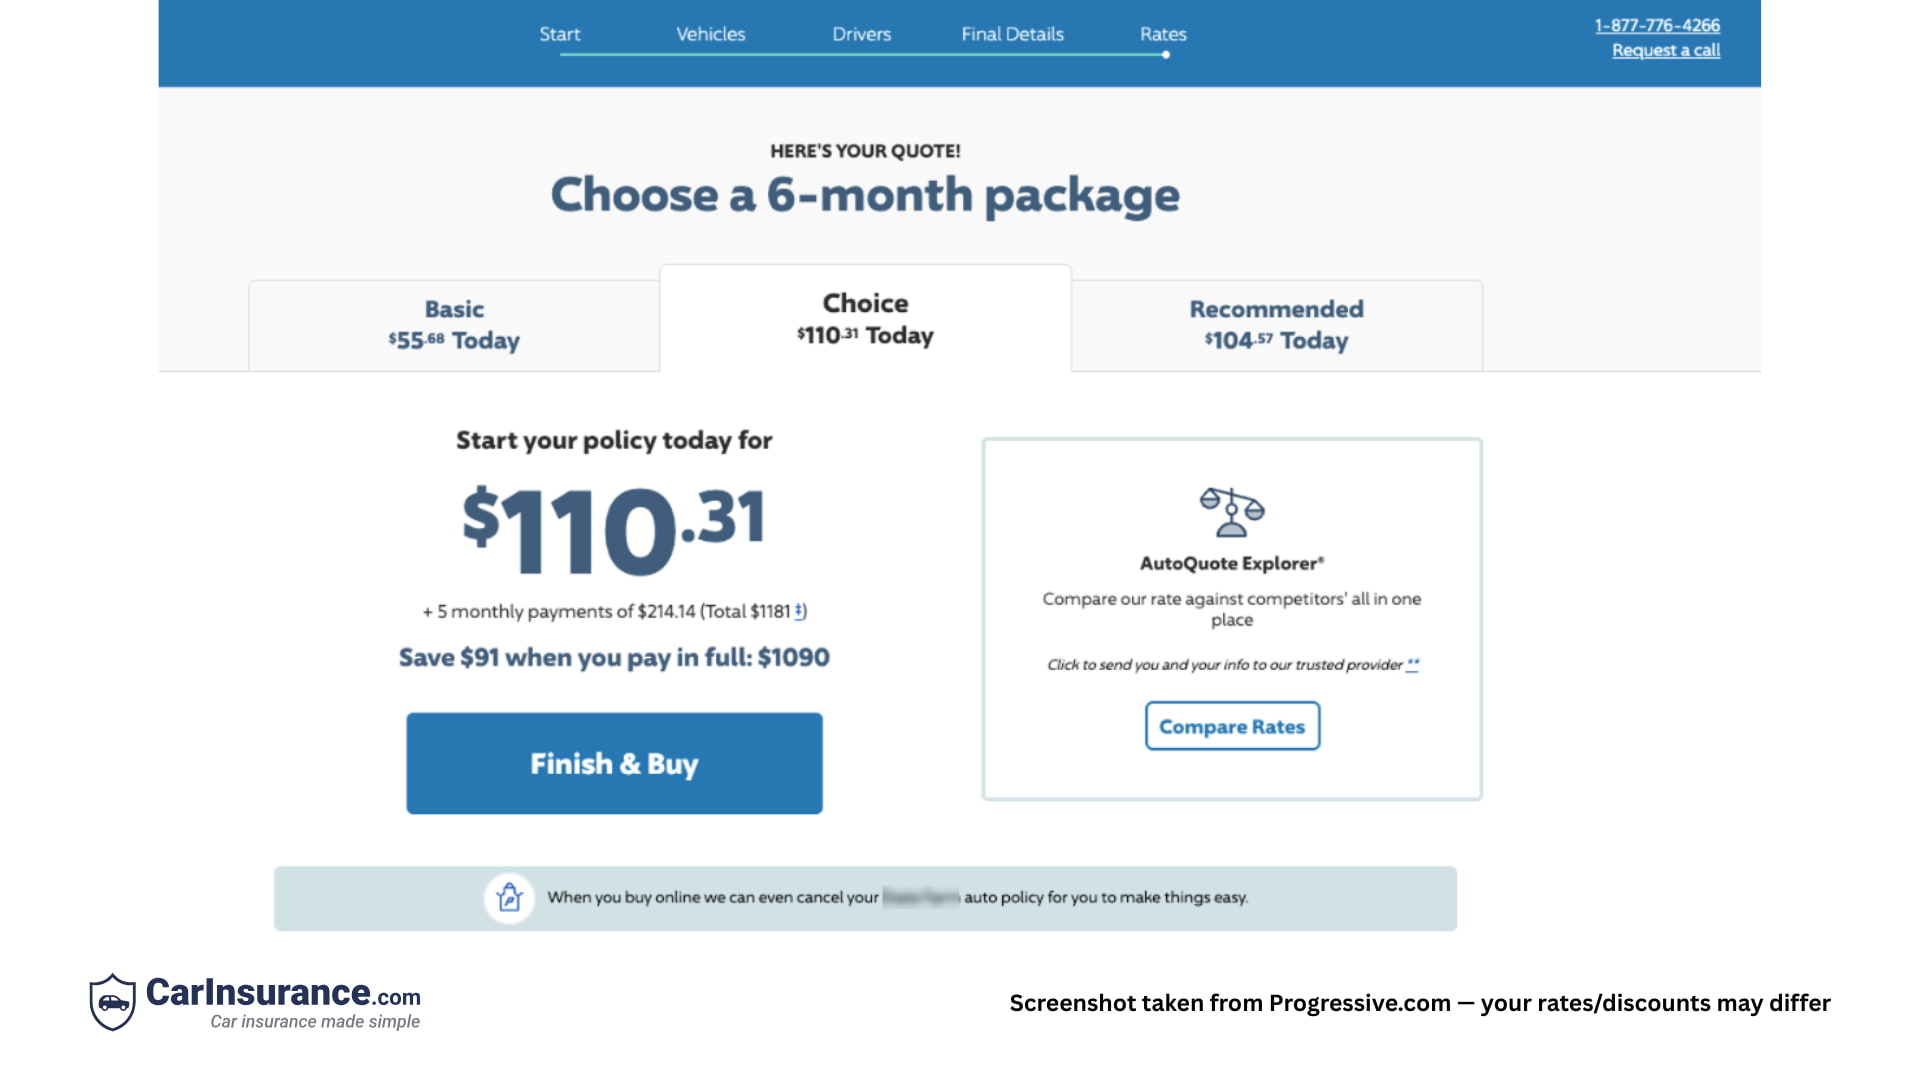
Progressive presented its suggested package with a big number, and I mean that literally: it said “$110.31” in big type, but in small print underneath it said “+ 5 monthly payments of $214.14 (Total $1181).” At first glance, I thought the rate I was being quoted was $110.31 per month, but that was just the amount to pay today to purchase the policy. Each subsequent payment would be $214.14.
This package included liability limits of 100/300/100, a $500 deductible for collision and comprehensive, plus uninsured/underinsured motorist liability coverage at 100/300 and medical payments coverage of $5,000 (MedPay is required in Pennsylvania).
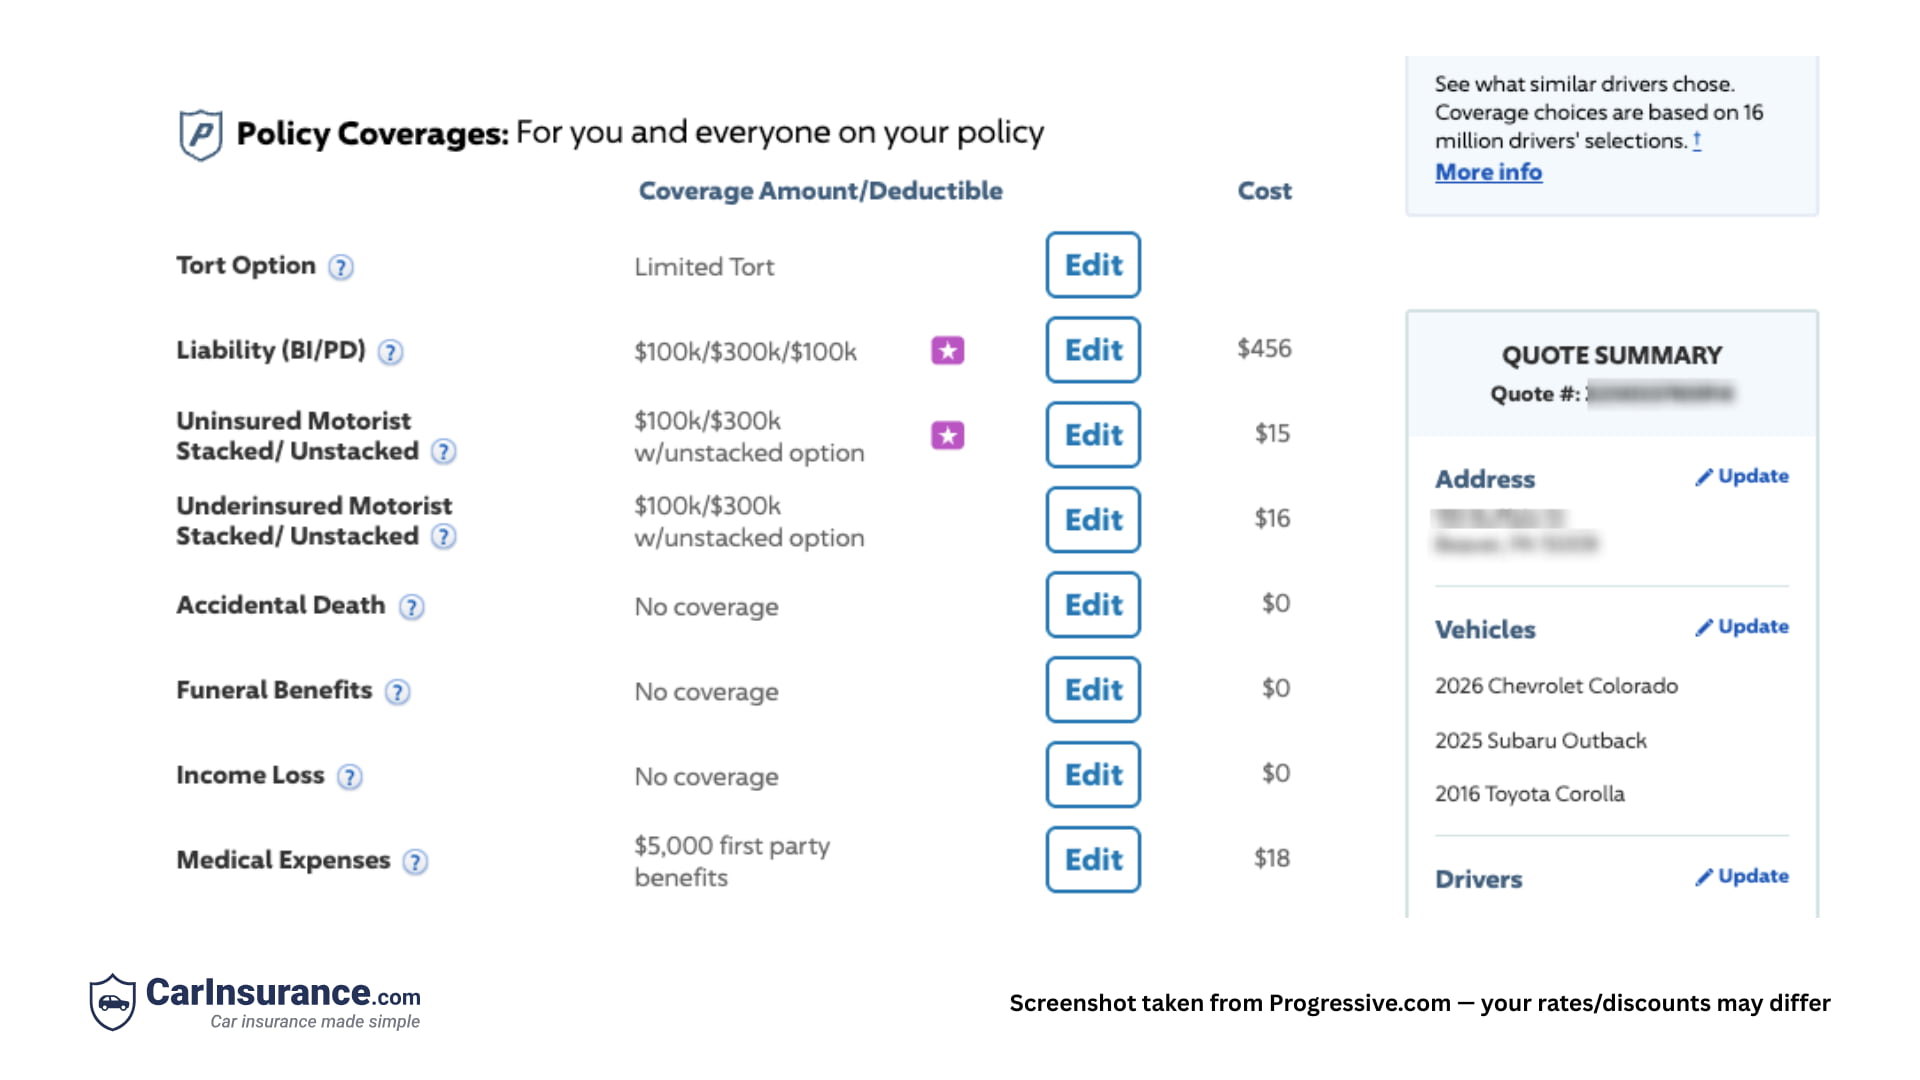
Here’s the kicker: the way Progressive presented the rates made it harder to compare the options. If I had divided the total six-month premium for my baseline package, $1,181, into six equal parts, the monthly rate would be $196.83 instead of $110.31 + (5 x $214.14). If you were in a rush, you might miss it, the way I did at first.
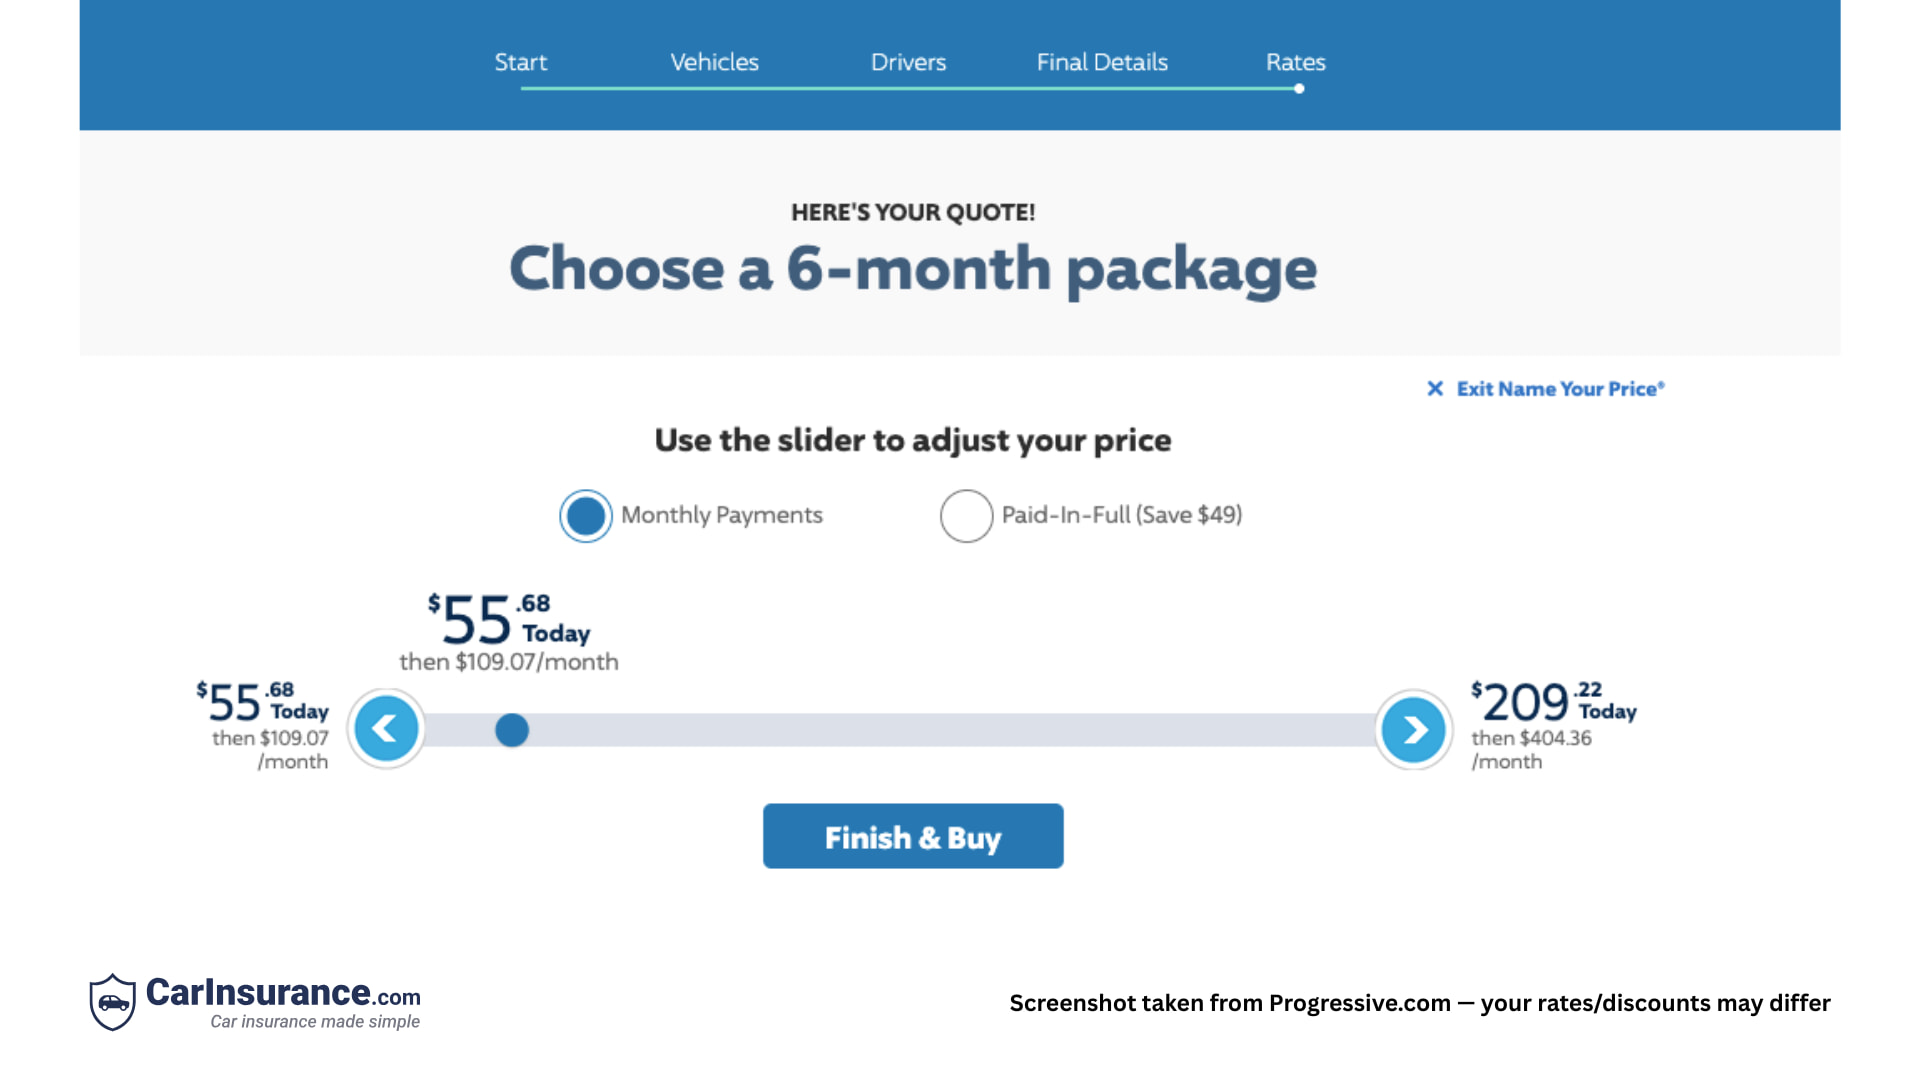
When I named a price about 20% lower than $110.31, the tool offered $55.68 today and then $109.07 per month. For that price, I got state minimum liability coverage with limits at 15/30/5, $5,000 in MedPay coverage, and a $2,000 deductible on my ‘25 Outback and my husband’s ‘26 Colorado. The tool also removed UM/UIM and the comprehensive and collision coverage from my son’s 10-year-old Corolla to meet that price.
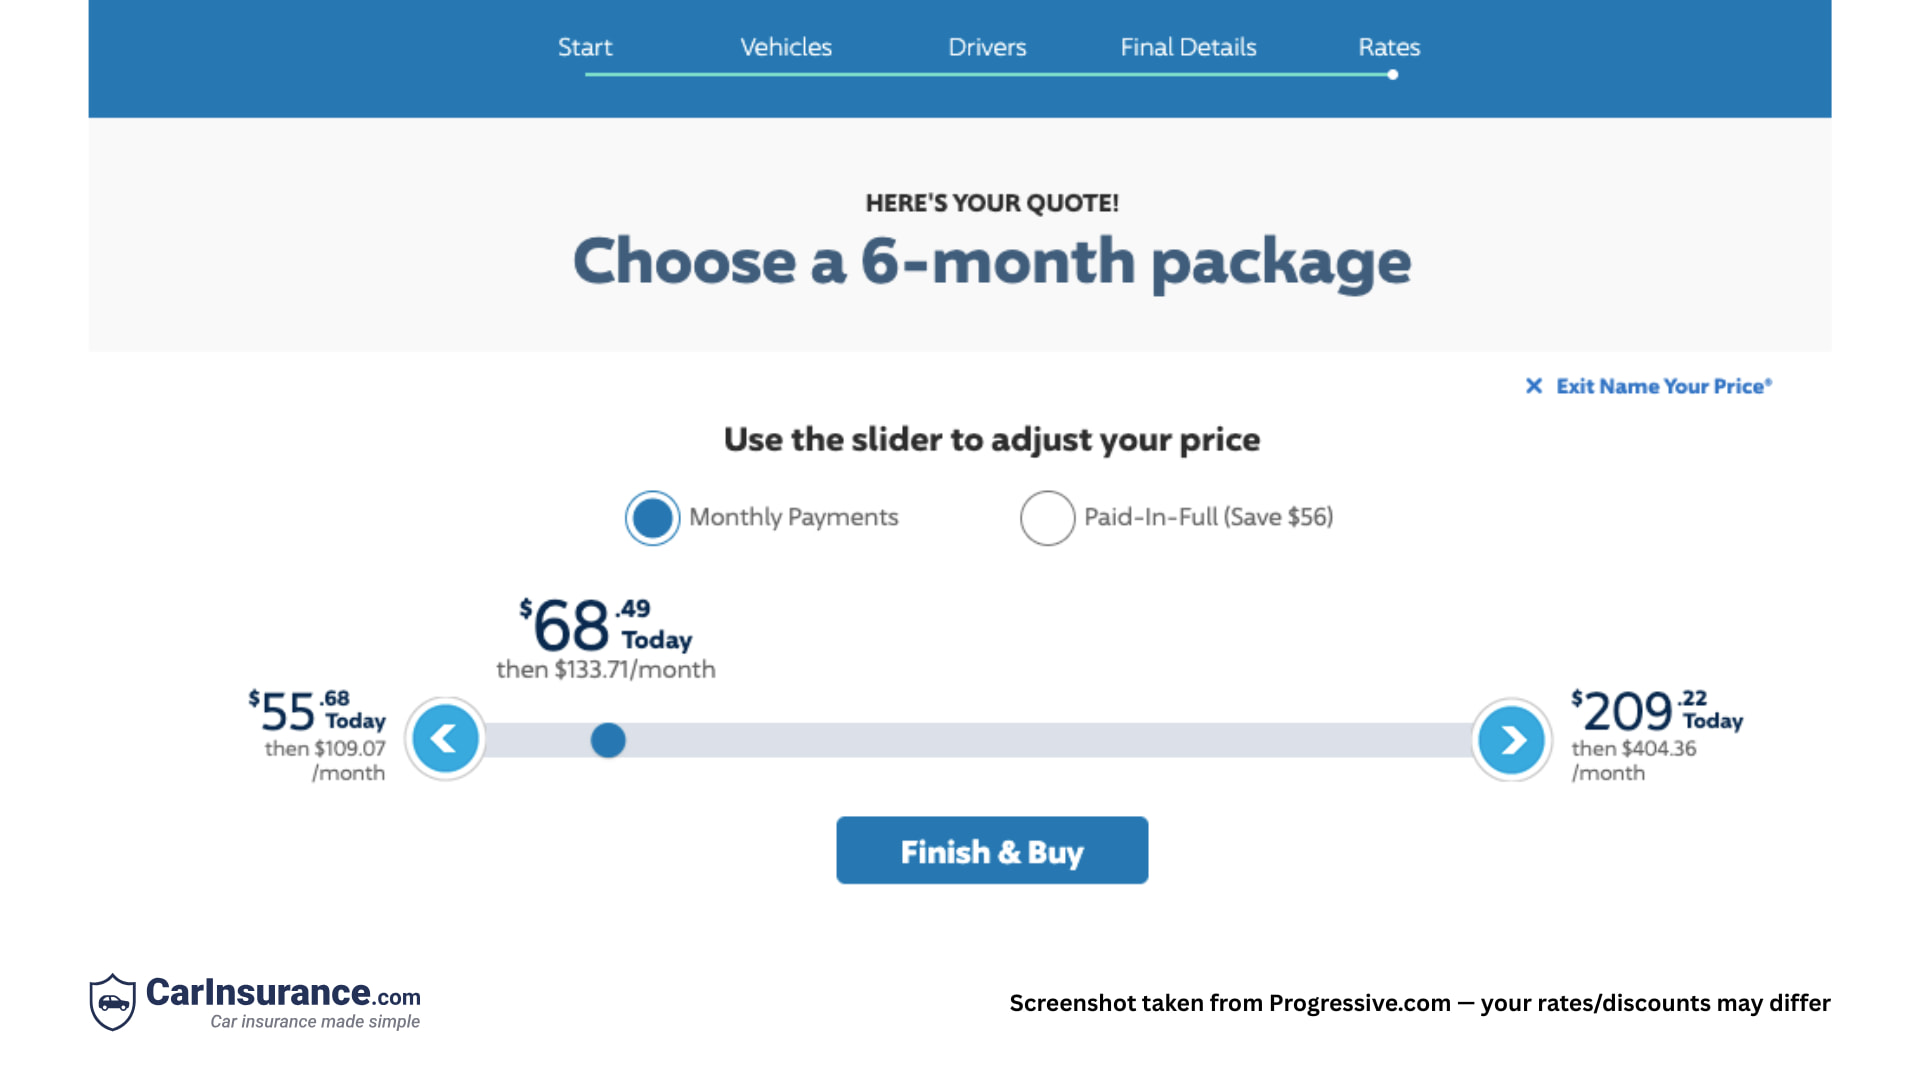
When I slid the price what I thought was 20% above the suggested package ($110.31, Progressive offered me $68.49 today, then $133.71 per month, for a total of $737. This rate got me state-minimum liability coverage and a $1,000 deductible for the two newer cars.
Conclusion
Name Your Price can be a good way to see how much protection you can buy with your budget at Progressive. Just make sure you read the prices carefully, and look for your true total, which can be hard to find. The first number you see may not be the real monthly price, which could give you sticker shock when it’s time to make payment No. 2.
Liability is one of the first things Progressive cuts when lowering the price, but don’t let it lead you to state minimum coverage just to save a few dollars a month. Raise your deductible before you touch liability.
Your best bet is to treat whatever number you land on as the price to beat and check what other companies charge for the same coverage. It takes just a few minutes, and it’s one thing the tool can’t do for you.
Frequently Asked Questions
Is there a catch with Progressive’s Name Your Price tool?
One big catch is that a lower price usually means less coverage. The tool doesn’t discount Progressive’s rates; it trims your liability limits, raises deductibles or drops comprehensive and collision to hit your number. That’s fine if you know what’s being cut, but you could lose important liability coverage if you’re not paying attention. Compare the package against your current coverage before you buy.
Can existing Progressive customers use Name Your Price?
Progressive says Name Your Price is for new quotes. If you’re an existing customer, you can still get a new quote online and try it, or ask Progressive to adjust your coverage at renewal.
Is Name Your Price available in every state?
Not every state. Progressive says it’s available in most states, and state law limits what price and coverage it can offer. You can’t name a price below your state’s minimum liability requirement.
What’s the lowest price you can name with Progressive?
It varies, but the floor is your price for state minimum liability coverage. Based on Progressive’s 2026 averages, state-minimum liability costs about $752 a year, compared with $864 for 50/100/50 liability. By state, Progressive’s state-minimum average runs from $228 a year in South Dakota to $1,642 in Florida. The lowest price you could get depends on your ZIP code, age, car, and driving record.
Is Name Your Price worth using?
It’s worth using as a quick way to remix different options to see what your budget buys at Progressive. But it’s not useful for finding the cheapest policy because it can’t compare other companies. I liked seeing how different coverage options affected the price, but I thought the price breakdown should have been more transparent.
Resources & methodology
Sources
- North Carolina Department of Motor Vehicles. “Liability Insurance.” Accessed October 2026.
- Virginia Department of Motor Vehicles. “ Insurance Requirements.” Accessed October 2026.
- Maine Bureau of Insurance. “Insurance Required by Law.” Accessed October 2026.
- Alaska Department of Motor Vehicles. “Mandatory Insurance.” Accessed October 2026.
- National Association of Insurance Commissioners. “Auto Insurance.” Accessed October 2026.
Methodology
CarInsurance.com’s State of Auto Insurance report, which analyzes rate data from Quadrant Information Services (2026), provided the average annual premiums on this page. Rates are for a 40-year-old male and female driver with a clean record and good credit, insuring a 2025 Honda Accord LX, at these coverage levels: state minimum liability; 50/100/50 liability; and 100/300/100 with $250, $500, and $1,000 comprehensive and collision deductibles. State figures cover 42 states and Washington, D.C.
Averages are for comparison only; your own price depends on your details. Our test of the Name Your Price tool was run by Mary Beth Eastman using rates for a household with two married adults and one teen driver in Pennsylvania, using a 2025 Subaru Outback, a 2026 Chevy Colorado, and a 2016 Toyota Corolla.

 Still have a question? Ask our experts
Get advice from an experienced insurance professional. Our experts will help you navigate your insurance questions with clarity and confidence.
Browse all FAQs